
HR 2198 Re-checks Congress.gov for new actions and updates the bill's status, and fills in any sponsors, committees, or related bills that are missing. It does not re-pull sponsors/cosponsors/committees/related — those rarely change — and it skips all work if nothing has changed upstream, so it's cheap to click.
To amend the Internal Revenue Code of 1986 to restore the taxable REIT subsidiary asset test.
To amend the Internal Revenue Code of 1986 to restore the taxable REIT subsidiary asset test.
Summary
- Increases the taxable REIT subsidiary asset limit from 20 percent to 25 percent under the Internal Revenue Code
- This permits REITs to allocate a higher percentage of their total assets to taxable subsidiaries
- The provision is effective for taxable years beginning after December 31, 2025
AI-generated plain-language summary of the bill text — neutral, and may be imperfect. See the full text below for the exact wording.
Sponsor (1)
-
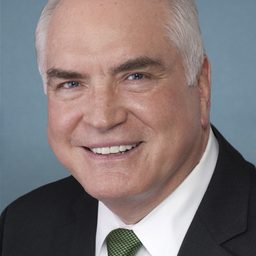 Rep. Kelly, Mike (R-PA) [#16]
20 cosponsors
-
 Rep. Buchanan, Vern (R-FL) [#16]
-
 Rep. Carey, Mike (R-OH) [#15]
-
 Rep. Davis, Danny K. (D-IL) [#7]
-
 Rep. DelBene, Suzan K. (D-WA) [#1]
-
 Rep. Estes, Ron (R-KS) [#4]
-
 Rep. Feenstra, Randy (R-IA) [#4]
-
 Rep. Fitzpatrick, Brian K. (R-PA) [#1]
-
 Rep. Hern, Kevin (R-OK) [#1]
-
 Rep. Kustoff, David (R-TN) [#8]
-
 Rep. LaHood, Darin (R-IL) [#16]
-
 Rep. Malliotakis, Nicole (R-NY) [#11]
-
 Rep. Moore, Blake D. (R-UT) [#1]
-
 Rep. Moore, Gwen (D-WI) [#4]
-
 Rep. Moran, Nathaniel (R-TX) [#1]
-
 Rep. Murphy, Gregory F. (R-NC) [#3]
-
 Rep. Panetta, Jimmy (D-CA) [#19]
-
 Rep. Schneider, Bradley Scott (D-IL) [#10]
-
 Rep. Smith, Adrian (R-NE) [#3]
-
 Rep. Suozzi, Thomas R. (D-NY) [#3]
-
 Rep. Tenney, Claudia (R-NY) [#24]
Money behind the sponsor
Top reported contributors to Mike Kelly’s campaign committee (2024 cycle) — who funds the bill’s sponsor, not a claim about this bill. Data from FEC.
- Employer not reported $43,700
- THE PARKER FOUNDATION $13,200
- LINDY PAVING INC. $8,800
- GREATER PITTSBURGH AUTO DEALERS ASSOCI $8,300
- ANDERSON COACH & TRAVEL $8,300
Organizations whose employees gave the most — itemized individual contributions grouped by the donor’s reported employer (FEC Schedule A). Full finance for Mike Kelly → · Outside spending →
Actions (2)
- Mar 18, 2025 Referred to the House Committee on Ways and Means. · house
- Mar 18, 2025 Introduced in House
Full text
IN THE HOUSE OF REPRESENTATIVES
March 18, 2025
Mr. Kelly of Pennsylvania (for himself, Mr. Schneider, Mr. Feenstra, Mr. Panetta, Mr. LaHood, Ms. Moore of Wisconsin, Mr. Moore of Utah, Mr. Davis of Illinois, Ms. Tenney, Ms. DelBene, Mr. Fitzpatrick, Mr. Suozzi, Mr. Buchanan, Mr. Murphy, Mr. Smith of Nebraska, and Mr. Estes) introduced the following bill; which was referred to the Committee on Ways and Means
A BILL
To amend the Internal Revenue Code of 1986 to restore the taxable REIT subsidiary asset test.
Be it enacted by the Senate and House of Representatives of the United States of America in Congress assembled,
SECTION 1. RESTORATION OF TAXABLE REIT SUBSIDIARY ASSET TEST.
(a) In General.—Section 856(c)(4)(B)(ii) of the Internal Revenue Code of 1986 is amended by striking “20 percent” and inserting “25 percent”.
(b) Effective Date.—The amendment made by this section shall apply to taxable years beginning after December 31, 2025. <all>
Text versions (1)
Bills are re-published as they move (Introduced → Reported → Engrossed → Enrolled …). Each stage below is a separate text; pick two to see what changed. Data from Congress.gov.
Similar bills (6)
Bills with similar text or summary — includes reintroductions across Congresses. Ranked by semantic similarity of the bill text (computed locally); a neutral discovery aid, not a claim the bills are duplicates.
Comments