
S 4639 Re-checks Congress.gov for new actions and updates the bill's status, and fills in any sponsors, committees, or related bills that are missing. It does not re-pull sponsors/cosponsors/committees/related — those rarely change — and it skips all work if nothing has changed upstream, so it's cheap to click.
IRS Whistleblower Program Improvement Act
To provide additional support to whistleblowers who report information about noncompliance with Federal tax laws.
Summary
- Changes the Tax Court's review of IRS whistleblower award determinations from an appeal to a review, conducted de novo and based on the administrative record plus any newly discovered or previously unavailable evidence.
- Exempts IRS whistleblower awards under Internal Revenue Code section 7623 from sequestration reductions under the Balanced Budget and Emergency Deficit Control Act of 1985.
- Requires whistleblowers to proceed anonymously in Tax Court proceedings unless the court finds that the public interest in disclosure outweighs the potential harm to the whistleblower.
- Requires the annual IRS whistleblower report to include a list and description of up to 10 top tax avoidance schemes disclosed by whistleblowers during the year.
- Adds interest at the overpayment rate to whistleblower awards when the IRS has not issued a preliminary award recommendation within a set period after collections and the related tax matters are resolved, effective 180 days after enactment.
- Corrects the above-the-line deduction for attorney's fees in IRC section 62(a)(21)(A)(i) so that it refers to all of section 7623, not only subsection (b), for taxable years ending after enactment.
AI-generated plain-language summary of the bill text — neutral, and may be imperfect. See the full text below for the exact wording.
Sponsor (1)
-
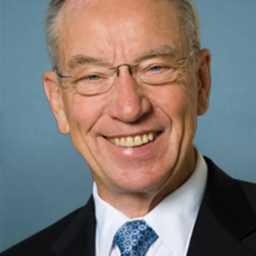 Sen. Grassley, Chuck (R-IA)
Actions (2)
- May 21, 2026 Read twice and referred to the Committee on Finance. · senate
- May 21, 2026 Introduced in Senate
Full text
IN THE SENATE OF THE UNITED STATES
May 21, 2026
Mr. Grassley (for himself and Mr. Wyden) introduced the following bill; which was read twice and referred to the Committee on Finance
A BILL
To provide additional support to whistleblowers who report information about noncompliance with Federal tax laws.
Be it enacted by the Senate and House of Representatives of the United States of America in Congress assembled,
SECTION 1. SHORT TITLE.
This Act may be cited as the “IRS Whistleblower Program Improvement Act”.
SEC. 2. STANDARD AND SCOPE OF REVIEW OF WHISTLEBLOWER AWARD DETERMINATIONS.
(a) In General.—Paragraph (4) of section 7623(b) of the Internal Revenue Code of 1986 is amended—
(1) by striking “appealed to” and inserting “reviewed by”; and
(2) by adding at the end the following: “Any review by the Tax Court under the preceding sentence shall be de novo and shall be based on the administrative record established at the time of the original determination and any additional newly discovered or previously unavailable evidence.”.
(b) Conforming Amendment.—The heading of paragraph (4) of section 7623(b) of the Internal Revenue Code of 1986 is amended by striking “Appeal” and inserting “Review”.
(c) Effective Date.—The amendments made by this section shall apply to petitions under section 7623(b)(4) of the Internal Revenue Code of 1986 which are pending on, or filed on or after, the date of the enactment of this Act.
SEC. 3. EXEMPTION FROM SEQUESTRATION.
(a) In General.—Section 255 of the Balanced Budget and Emergency Deficit Control Act of 1985 (2 U.S.C. 905) is amended—
(1) by redesignating subsection (k) as subsection (l); and
(2) by inserting after subsection (j) the following:
“(k) Awards to Whistleblowers.—An award authorized under section 7623 of the Internal Revenue Code of 1986 shall be exempt from reduction under any order issued under this part.”.
(b) Applicability.—The amendment made by this section shall apply to any sequestration order issued under the Balanced Budget and Emergency Deficit Control Act of 1985 (2 U.S.C. 900 et seq.) after the date of enactment of this Act.
SEC. 4. WHISTLEBLOWER PRIVACY PROTECTIONS.
(a) In General.—Paragraph (6) of section 7623(b) of the Internal Revenue Code of 1986 is amended by adding at the end the following new subparagraph:
“(D) Whistleblower anonymity before the tax court.—Notwithstanding sections 7458 and 7461, a whistleblower shall proceed anonymously before the Tax Court for all proceedings under this section absent a finding by the Tax Court that a societal interest exists for disclosing the whistleblower’s identity which exceeds the potential harm disclosure could cause to the whistleblower.”.
(b) Effective Date.—The amendment made by this section shall apply to petitions filed with the Tax Court which are pending on, or filed on or after, the date of the enactment of this Act.
SEC. 5. MODIFICATION OF IRS WHISTLEBLOWER REPORT.
(a) In General.—Section 406(c) of division A of the Tax Relief and Health Care Act of 2006 is amended by striking “such use,” in paragraph (1) and inserting “such use (which shall include a list and descriptions of the top tax avoidance schemes, not to exceed 10, disclosed by whistleblowers during such year),”.
(b) Effective Date.—The amendments made by this section shall apply to reports for fiscal years ending after the enactment of this Act.
SEC. 6. INTEREST ON WHISTLEBLOWER AWARDS.
(a) In General.—Section 7623(b) of the Internal Revenue Code of 1986 is amended by adding at the end the following new paragraph:
“(7) Interest.—
“(A) In general.—If the Secretary has not provided notice to an individual described in paragraph
(1) of a preliminary award recommendation before the applicable date, the amount of any award under this subsection shall include interest from such date at the overpayment rate under section 6621(a).
“(B) Exception.—No interest shall accrue under this paragraph after the date on which the Secretary provides notice to the individual of a preliminary award recommendation.
“(C) Applicable date.—For purposes of this paragraph, the applicable date is the date that is 12 months after the first date on which—
“(i) all of the proceeds resulting from actions subject to the award recommendation have been collected, and
“(ii) either—
“(I) the statutory period for filing a claim or suit for refund has expired, or
“(II) the taxpayers subject to the actions and the Secretary have agreed with finality to the tax or other liabilities for the periods at issue, and either the taxpayers have waived the right to file a claim or suit for refund or any claim or suit for refund has been resolved.”.
(b) Effective Date.—
(1) In general.—The amendments made by this section shall take effect 180 days after the date of the enactment of this Act.
(2) Special rule.—If, as of the date described in paragraph (1)—
(A) the Secretary has not provided notice to the individual of a preliminary award recommendation as described in paragraph (7)(A) of section 7623(b) of the Internal Revenue Code of 1986, as added by this Act, and
(B) the applicable date provided in paragraph
(7)(C) of such section, as so added, has passed, the applicable date for purposes of such paragraph (7)(C) is the date that is 12 months after the date described in paragraph (1).
SEC. 7. CORRECTION REGARDING DEDUCTIONS FOR ATTORNEY’S FEES.
(a) In General.—Section 62(a)(21)(A)(i) of the Internal Revenue Code of 1986 is amended by striking “7623(b)” and inserting “7623”.
(b) Effective Date.—The amendment made by this section shall apply to taxable years ending after the date of the enactment of this Act. <all>
Comments