
S 3587 Re-checks Congress.gov for new actions and updates the bill's status, and fills in any sponsors, committees, or related bills that are missing. It does not re-pull sponsors/cosponsors/committees/related — those rarely change — and it skips all work if nothing has changed upstream, so it's cheap to click.
No Tax on Wrongful Delay Act of 2026
To amend the Internal Revenue Code of 1986 to provide an exemption from gross income for interest paid to taxpayers by the Internal Revenue Service following an audit or litigation in which the taxpayer prevailed.
Summary
- Exempts from taxation any interest paid by the Internal Revenue Service to taxpayers on overpaid taxes following an IRS audit, examination, or taxpayer lawsuit for credit or refund of taxes.
- Exempts from taxation any interest paid by the IRS to taxpayers following a civil action by the United States for collection or recovery of taxes.
- Takes effect for taxable years beginning after December 31, 2025.
AI-generated plain-language summary of the bill text — neutral, and may be imperfect. See the full text below for the exact wording.
Sponsor (1)
-
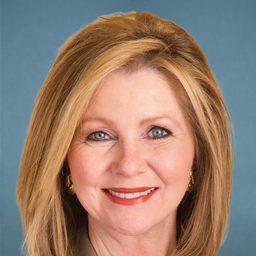 Sen. Blackburn, Marsha (R-TN)
Actions (2)
- Jan 7, 2026 Read twice and referred to the Committee on Finance. · senate
- Jan 7, 2026 Introduced in Senate
Full text
IN THE SENATE OF THE UNITED STATES
January 7, 2026
Mrs. Blackburn introduced the following bill; which was read twice and referred to the Committee on Finance
A BILL
To amend the Internal Revenue Code of 1986 to provide an exemption from gross income for interest paid to taxpayers by the Internal Revenue Service following an audit or litigation in which the taxpayer prevailed.
Be it enacted by the Senate and House of Representatives of the United States of America in Congress assembled,
SECTION 1. SHORT TITLE.
This Act may be cited as the “No Tax on Wrongful Delay Act of 2026”.
SEC. 2. EXEMPTION FROM GROSS INCOME FOR INTEREST PAID TO TAXPAYERS FOLLOWING AUDIT OR LITIGATION.
(a) In General.—Part III of subchapter B of chapter 1 of the Internal Revenue Code of 1986 is amended by inserting before section 140 the following new section:
“SEC. 139M. INTEREST PAID TO TAXPAYERS FOLLOWING AN AUDIT OR LITIGATION.
“Gross income shall not include any interest which, pursuant to section 6611, is required to be paid upon any overpayment in respect of any internal revenue tax following—
“(1) an examination pursuant to the provisions of section 7602,
“(2) any suit or proceeding brought by the taxpayer for the credit or refund of taxes, or
“(3) any civil action commenced by the United States for the collection or recovery of taxes.”.
(b) Conforming Amendment.—The table of sections for part III of subchapter B of chapter 1 of the Internal Revenue Code of 1986 is amended by inserting before the item relating to section 140 the following new item:
“Sec. 139M. Interest paid to taxpayers following an audit or litigation.”.
(c) Effective Date.—The amendments made by this section shall apply to taxable years beginning after December 31, 2025. <all>
Comments