
HR 2266 Re-checks Congress.gov for new actions and updates the bill's status, and fills in any sponsors, committees, or related bills that are missing. It does not re-pull sponsors/cosponsors/committees/related — those rarely change — and it skips all work if nothing has changed upstream, so it's cheap to click.
To amend the Internal Revenue Code of 1986 to increase the threshold amounts for inclusion of Social Security benefits in income.
Summary
- Increases the income thresholds at which Social Security benefits are included in taxable income from $25,000 to $34,000 for single filers and from $32,000 to $68,000 for joint filers.
- Indexes these income thresholds to the cost-of-living adjustment beginning in 2026.
- Requires annual appropriations to Social Security and Railroad Retirement trust funds to offset any reduction in transfers resulting from the increased thresholds.
- Requires pro rata rescissions of non-security discretionary appropriations beginning in fiscal year 2027 equal to the total cost of the tax relief for that fiscal year.
- Requires the Office of Management and Budget to publish annual reports detailing rescissions made under this section beginning January 1, 2028.
- Applies to taxable years beginning after December 31, 2025.
AI-generated plain-language summary of the bill text — neutral, and may be imperfect. See the full text below for the exact wording.
Sponsor (1)
-
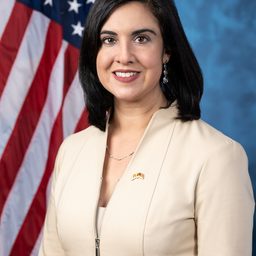 Rep. Malliotakis, Nicole (R-NY) [#11]
Money behind the sponsor
Top reported contributors to Nicole Malliotakis’s campaign committee (2024 cycle) — who funds the bill’s sponsor, not a claim about this bill. Data from FEC.
- WCAS $20,400
- BLACKSTONE $13,200
- APOLLO GLOBAL MANAGEMENT $11,117
- GRUSS & CO LLC $10,971
- CADDELL DRY DOCK $10,300
Organizations whose employees gave the most — itemized individual contributions grouped by the donor’s reported employer (FEC Schedule A). Full finance for Nicole Malliotakis → · Outside spending →
Actions (2)
- Mar 21, 2025 Referred to the Committee on Ways and Means, and in addition to the Committee on Appropriations, for a period to be subsequently determined by the Speaker, in each case for consideration of such provisions as fall within the jurisdiction of the committee concerned. · house
- Mar 21, 2025 Introduced in House
Similar bills (6)
Bills with similar text or summary — includes reintroductions across Congresses. Ranked by semantic similarity of the bill text (computed locally); a neutral discovery aid, not a claim the bills are duplicates.
Text versions (1)
Bills are re-published as they move (Introduced → Reported → Engrossed → Enrolled …). Each stage below is a separate text; pick two to see what changed. Data from Congress.gov.
Full text
IN THE HOUSE OF REPRESENTATIVES
March 21, 2025
Ms. Malliotakis introduced the following bill; which was referred to the Committee on Ways and Means, and in addition to the Committee on Appropriations, for a period to be subsequently determined by the Speaker, in each case for consideration of such provisions as fall within the jurisdiction of the committee concerned
A BILL
To amend the Internal Revenue Code of 1986 to increase the threshold amounts for inclusion of Social Security benefits in income.
Be it enacted by the Senate and House of Representatives of the United States of America in Congress assembled,
SECTION 1. SHORT TITLE.
This Act may be cited as the “Reducing Excessive Taxation and Inefficiencies by Reforming Elder Exemptions to Support Fairness, Inflation Relief, and Simpler Taxes Act” or the “RETIREES FIRST Act”.
SEC. 2. INCREASE IN THRESHOLD AMOUNTS FOR INCLUSION OF SOCIAL SECURITY BENEFITS IN INCOME.
(a) In General.—Subsection (a) of section 86 of the Internal Revenue Code of 1986 is amended to read as follows:
“(a) In General.—Gross income for the taxable year of any taxpayer described in subsection (b) (notwithstanding section 207 of the Social Security Act) includes Social Security benefits in an amount equal to the lesser of—
“(1) 85 percent of the Social Security benefits received during the taxable year, or
“(2) 85 percent of the excess described in subsection
(b)(1).”.
(b) Base Amount.—Subsection (c) of section 86 of such Code is amended to read as follows:
“(c) Base Amount.—
“(1) In general.—For purposes of this section, the term ‘base amount’ means—
“(A) except as otherwise provided in this subsection, $34,000,
“(B) $68,000 in the case of a joint return, and
“(C) zero in the case of a taxpayer who—
“(i) is married as of the close of the taxable year (within the meaning of section 7703) but does not file a joint return for such year, and
“(ii) does not live apart from his spouse at all times during the taxable year.
“(2) Inflation adjustment.—
“(A) In general.—In the case of any taxable year beginning after 2025, each of the dollar amounts in paragraph (1) shall be increased by an amount equal to—
“(i) such dollar amount, multiplied by
“(ii) the cost-of-living adjustment determined under section 1(f)(3) for the calendar year, determined by substituting ‘calendar year 2024’ for ‘calendar year 2016’ in subparagraph (A)(ii) thereof.
“(B) Rounding.—If any amount determined under subparagraph (A) is not a multiple of $1,000, such amount shall be rounded to the nearest multiple of $1,000.”.
(c) Social Security Trust Funds Held Harmless.—There are hereby appropriated (out of any money in the Treasury not otherwise appropriated) for each fiscal year to each fund under the Social Security Act or the Railroad Retirement Act of 1974 an amount equal to the reduction in the transfers to such fund for such fiscal year by reason of the amendments made by this section.
(d) Effective Date.—The amendments made by this section shall apply to taxable years beginning after December 31, 2025.
SEC. 3. REALLOCATING NON-SECURITY DISCRETIONARY APPROPRIATIONS TO SUPPORT RETIREE TAX RELIEF.
(a) Rescission.—Subject to subsection (c), for fiscal year 2027, and each fiscal year thereafter, effective on the day after the date on which appropriations are made available through September 30 of the applicable fiscal year for the entire Federal Government, there is rescinded an amount equal to the total cost for such fiscal year, on a pro rata basis, from amounts made available through regular appropriation Acts.
(b) Regular Appropriation Act.—For purposes of this section, the term “regular appropriation Act”—
(1) means an annual appropriation Act (as described in section 105 of title 1, United States Code) providing new budget authority (as defined in section 3 of the Congressional Budget and Impoundment Control Act of 1974 (2 U.S.C. 622)) for the programs, projects, and activities under the jurisdiction of a subcommittee of the Committee on Appropriations of the Senate; and
(2) includes—
(A) a title, division, or other subdivision of an Act or resolution that, if it were a separate Act, would be an Act described in paragraph (1); and
(B) a resolution or Act, or a title, division, or other subdivision of a resolution or Act, making continuing appropriations for all, or a portion of, a fiscal year.
(c) Exclusion.—Subsection (a) shall not apply with respect to any discretionary appropriations included in the security category (as defined in Section 250(c) of the Balanced Budget and Emergency Deficit Control Act of 1985 (2 U.S.C. 900(c))).
(d) Total Cost.—For purposes of this section, the term “total cost” means, with respect to a fiscal year, an amount (as determined by the Secretary of the Treasury) equal to the total reduction in the transfers to each fund under the Social Security Act or the Railroad Retirement Act of 1974 for such fiscal year by reason of the amendments made by section 2(b) (as determined without respect to any appropriation made pursuant to section 2(c)).
(e) OMB Report.—Not later than January 1, 2028, and annually thereafter, the Director of the Office of Management and Budget shall publish a report detailing any rescissions made under this section with respect to the most recently completed fiscal year. <all>
Comments